Consistently monitoring the waters…
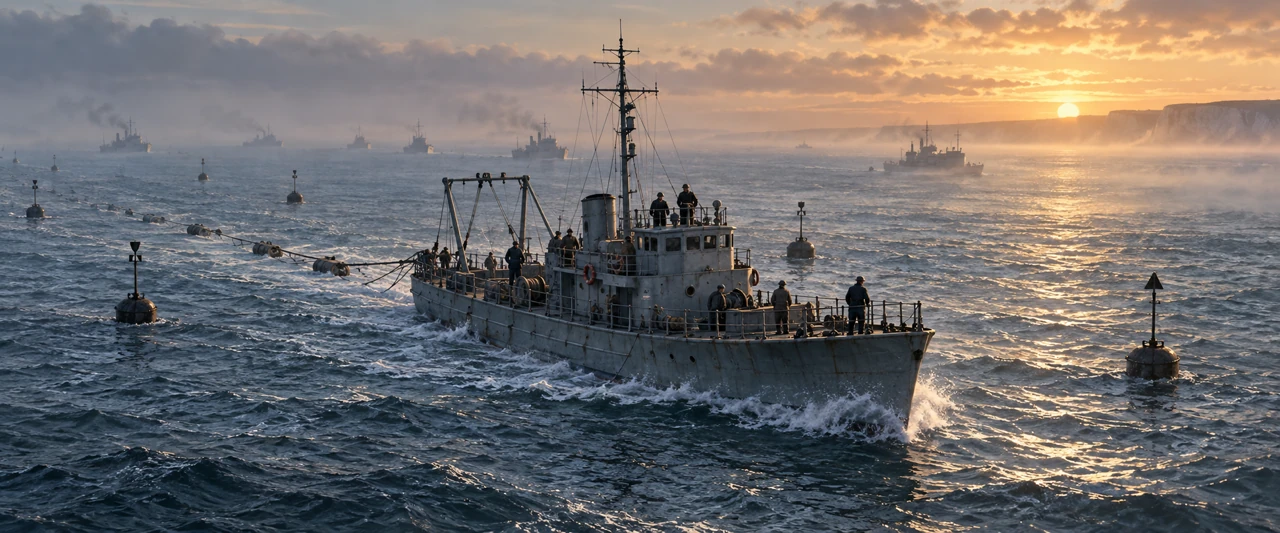
Before the Allied landing forces reached Normandy, minesweepers went ahead to clear and mark their approach.
During Operation Neptune, ten channels were swept through German minefields. Off Utah Beach, Mine Squadron 7 worked in formation, overlapping its sweeping gear and marking the passage with lighted buoys.
Early on June 6, the crews watched the bombardment ships enter the areas they had swept.
The work continued after the landings. Those waters required repeated checking as the operation progressed.
That discipline offers a useful lesson for how we approach markets. A plan establishes where we expect to go … consistently monitoring new information helps us navigate the route and determine when to adjust our positioning.
Last month, in The Plan Meets the Signal, we described an economy moving toward accelerating growth and inflation. We also emphasized that our investment decisions would follow the signals based on the rate of change in price, volume, and volatility—even when they differed from what typically works in a particular economic environment.
October has brought evidence supporting both parts of that framework.
September’s inflation acceleration is now reported data. Several growth measures have strengthened. Yet credit spreads are widening, housing continues to deteriorate, and parts of the equity market are weakening.
Meanwhile, current monthly projections place five of the first six months of 2027 in Quad 4 ... decelerating growth and inflation.
Markets are forward-looking, often responding to what investors expect before it appears in the economic data. That makes it important to consider what may lie ahead—and the probabilities of different outcomes—as we manage the exposures we hold today.
The data inform our expectations … the signals determine our response.
The forecast becomes the report
Last month, we described a change in inflation’s direction.
Headline CPI had slowed from +4.25% YoY in May to +3.36% in July, before edging higher to +3.40% in August. The September nowcast we cited called for +3.74%.
The September report came in at +3.74% … (well done Hedgeye … well done)
That represents a +34-basis-point acceleration from August and a +38-basis-point increase from July’s low.
The monthly increase also strengthened, from +0.40% to +0.65%.
The direction matters. Inflation’s annual rate had been decelerating. It has since turned higher.
And the acceleration extends beyond the headline:
| September inflation measure | MoM change | Previous YoY rate | September YoY rate | Change in YoY rate |
|---|---|---|---|---|
| Headline CPI | +0.65% | +3.40% | +3.74% | +34 bps |
| Core CPI | +0.33% | +2.45% | +2.56% | +11 bps |
| CPI shelter | +0.39% | +3.04% | +3.22% | +18 bps |
| Headline producer prices | +1.30% | +5.44% | +6.34% | +90 bps |
| Core producer prices | +0.68% | +4.81% | +4.97% | +16 bps |
| Core import prices | +0.70% | +5.50% | +6.20% | +70 bps |
Energy remains a significant contributor. CPI energy prices increased +5.20% MoM, with annual inflation accelerating from +16.28% to +20.45%. Producer energy prices increased +11.27% MoM, pushing their annual rate from +24.31% to +35.55%.
But core consumer prices, core producer prices, and import prices excluding food and fuel also accelerated.
We should therefore be careful about explaining away the entire move as an energy story.
The business surveys reinforce that concern.
ISM Manufacturing Prices Paid increased +6.8 points to 77.9 in September. ISM Services Prices increased +1.4 points to 74.0, its highest level since July 2022.
Shelter adds another complication. Owners’ equivalent rent accelerated from +3.06% to +3.26% YoY, while rent of primary residence edged from +2.75% to +2.78%. The supplied research still shows Apartment List’s measure of market rents was still down −0.4% YoY in the research we reviewed, illustrating the different timing and coverage of market rents and CPI shelter measures.
Looking ahead, Hedgeye’s October inflation nowcast estimates headline CPI at +3.88% YoY, with a range of +3.77% to +3.99%. Relative to September’s +3.74%, that implies another +14 basis points of acceleration in the base case.
Those October figures remain estimates. But the current range continues to point higher.
Growth ... stronger in places, uneven underneath
Growth requires a more selective reading.
There is evidence of acceleration. Industrial production increased +0.66% MoM in September, its sixth consecutive monthly gain. Annual growth accelerated from +1.62% to +2.25% ... an improvement of +63 basis points.
Retail sales also strengthened, rising +0.77% MoM while annual growth accelerated from +5.56% to +6.29%.
| Growth measure | Latest period | Monthly change | Previous YoY rate | Latest YoY rate |
|---|---|---|---|---|
| Industrial production | September | +0.66% | +1.62% | +2.25% |
| Retail sales | September | +0.77% | +5.56% | +6.29% |
| Retail sales excluding autos | September | +0.90% | +6.34% | +7.19% |
| Retail control group | September | +0.15% | +4.61% | +4.72% |
| Factory orders excluding transportation | August | +0.26% | +9.63% | +10.29% |
| Nominal personal spending | August | +0.86% | +5.69% | +6.08% |
Though, the underlying composition matters.
Retail sales are nominal. Higher prices can increase the dollars spent without producing an equivalent increase in goods purchased. Gasoline-station sales rose +6.37% MoM in September, increasing their share of total retail sales from 8.65% to 9.13%.
The retail control group, which feeds into GDP calculations, increased a more modest +0.15% MoM. Its annual growth improved +11 basis points, compared with the headline’s +73-basis-point acceleration.
Both improved. They tell us different things about the strength of the move.
Similarly, August factory orders excluding transportation accelerated from +9.63% to +10.29% YoY, while headline factory-order growth slowed from +10.46% to +8.81%.
This is why we keep looking beneath the headline.
The ISM surveys offer another example. Manufacturing slipped −0.1 points to 54.5 in September, while services fell −0.5 points to 54.9. Both remained above 50, indicating expansion, but both headline indexes slowed.
- Within manufacturing, new orders improved +1.6 points to 55.3 and backlogs increased +4.6 points to 56.4.
- Within services, new orders declined −1.1 points to 59.8 and business activity fell −5.2 points to 56.5.
An economy can keep expanding while individual measures decelerate. Our task is to determine how those changes combine—and whether the balance is improving or deteriorating.
Limited layoffs, slower hiring
The labor data deserve the same care.
September nonfarm payrolls increased just +29,000. July and August were revised lower by a combined 62,000 jobs, leaving the three-month average at approximately +51,000.
Average hourly earnings increased +0.13% MoM, while annual growth slowed from +3.11% to +3.02%. Average weekly pay growth decelerated from +3.72% to +3.63% YoY.
Those are signs of softer hiring and wage growth.
Yet the latest unemployment-claims data continue to show limited layoffs. Initial claims fell 6,000 WoW to 194,000 for the week ended October 16. The four-week average declined to 197,750, down −13.2% YoY compared with −11.6% previously.
Continuing claims moved the other way, increasing 25,000 WoW to 1.728 million. Their four-week average remained down −12.3% YoY, although that decline narrowed slightly from −12.4%.
Hedgeye’s research showed payroll tax receipts up approximately +4.6% YoY through October 15.
We should acknowledge both sides. Hiring has weakened, but the claims data do not yet show a broad wave of job losses. That distinction matters for household income, spending, and the payroll contributions supporting investment flows.
Where pressure is already evident
Housing provides a clearer example of deterioration.
Mortgage applications declined −5.3% WoW in the week ended October 16, their seventh consecutive weekly decline. The annual contraction worsened from −37.2% to −40.4%.
Purchase applications fell −7.3% WoW, with their annual decline deepening from −16.1% to −17.9%. Refinancing applications were down −58.6% YoY.
The average 30-year mortgage rate eased 9 basis points to 7.41%, but that weekly relief did not reverse the decline in applications.
September pending home sales fell −7.3% MoM to a record-low index reading of 66.0. Their annual decline worsened from −4.74% to −12.63%. Purchase cancellations increased from 14.2% to 14.5%.
There were minor offsets … for example, existing-home sales increased +1.5% MoM, and the annual decline in total housing starts narrowed. But those improvements paled in comparison to the broader deterioration:
Single-family permits shifted from +1.5% to −4.8% YoY, while existing-home inventory increased +4.6% YoY.
Housing is already illustrating how expensive financing can restrain activity while other parts of the economy remain resilient.
Five out of six months
The current quarterly framework still projects Q4 reflation.
Hedgeye’s forward modeling estimates real GDP growth increasing from +2.12% YoY in Q3 to +2.37% in Q4, while quarterly headline inflation rises from +3.50% to +3.86%.
That combination is Quad 2.
The forward monthly path places five of the first six months of 2027 in Quad 4 (disinflation/deflation).
That combination deserves attention, awareness, repeated monitoring and preparation … WHY?!
For newer readers, in its simplest form, Quad 4 means growth and inflation decelerating simultaneously.
This does not automatically mean recession, economic contraction, or falling consumer prices. It does not guarantee automatic market crash, either.
HOWEVER, it is incredibly important to understand or at least be mindful of the fact that these are the underlying conditions which have brought US equities every modern-day crash over the last 30+ years.
Again, it doesn’t mean that they will crash … currently, we’re not calling for a crash … but:
- Markets don’t have to wait until January data … for they respond to current information while continually discounting future expectations.
- We’ll stick to our process and signals. SPY remains above our decision-making levels, and we remain invested in that exposure. The QQQs are dancing on our decision-making lines, so we’ve reduced our risk while retaining some exposure. IWM is below our decision-making levels, which is why we’ve been out of that position for some time.
As we explained last month, monthly projections and nowcasts provide a working map. They change as new information arrives. Monthly and quarterly classifications also summarize different periods, so a quarterly label can obscure important changes within the quarter.
The comparative bases matter as well. Strong spending, investment, and stimulus-supported activity eventually become the year-earlier figures against which future growth is measured. Sustaining acceleration becomes more difficult when those comparisons strengthen.
We will keep monitoring those estimates. We will also watch whether markets begin responding before the slowdown becomes clear in the reported data.
Credit deserves attention
Hedgeye’s October 26 research adds measurable evidence to that question.
High-yield option-adjusted spreads widened another +6 basis points over the preceding week, bringing the monthly increase to +63 basis points.
Over the same week, the two-year Treasury yield declined 3 basis points and the ten-year declined 8. Over the month, they were down 21 and 10 basis points, respectively.
In Hedgeye’s framework, Treasury yields had turned bearish over the shorter TRADE duration, while remaining bullish over the longer TREND duration. That is an emerging change, with longer-term confirmation still incomplete.
Leadership also shifted. Healthcare, represented by XLV, gained +1.5% over the week, while industrials, represented by XLI, declined −1.9%.
International weakness broadened the picture. Over three months, Philippine equities through EPHE fell −8.8%, and Indian equities through INDA lost −6.7% … though more importantly South Korean equities through EWY declined −23.6% while the U.S. dollar remained bullish on both TRADE and TREND.
These observations do not establish an inevitable credit crisis … though, they do warrant attention … WHY?!
EWY is the most liquid U.S. listed proxy for the KOSPI (South Korea’s broad stock index) which is not just heavily skewed towards the semiconductor industry … it’s frequently cited as THE global leading indicator or “weathervane” for the entire AI trade … suffice to say it is critically important to the AI (Artificial Intelligence) space.
The KOSPI most recently peaked on June 22, 2026, reaching a record high of 9,114.55 … it currently sits around 5,638 … roughly a 40% DECLINE in value in a 4-month time frame.
Adding insult to injury, the persistence of inflation further complicates the landscape. WTI oil increased +4.3% over the week and +28.5% over three months. Higher energy costs can pressure spending even as growth-sensitive assets begin weakening.
AI ... circling back on South Korea
South Korea’s semiconductor exposure makes its weakness particularly relevant to the AI investment cycle, especially as it pertains to AI financing. Capital-spending plans require funding.
Some companies building AI infrastructure are also helping fund the customers expected to use it, creating financial connections across the buildout.
The terms and availability of that funding matter to the durability of the investment cycle, particularly as credit conditions change.
A widening spread, a failed financing, or a weakening price trend adds information … and may signal growing stress.
If falling asset values reduce collateral available to lenders, a negative feedback loop could develop:
Falling asset values → less borrowing capacity → harder or more expensive financing → reduced investment or asset sales → further pressure on asset values.
The potential problem arises if/when those pressures begin to reinforce one another.
The Federal Reserve has already tightened policy, inflation remains elevated, and growth is projected to slow in 2027. If borrowing costs remain high while AI spending growth decelerates and credit spreads widen, companies that depend on outside funding could face a more difficult environment.
A sustained funding problem could affect investment plans, suppliers, lenders, and market confidence. These are all risks we are monitoring—not a completed chain of events.
For us, the questions are measurable: Do credit spreads continue to widen? Does financing become more expensive or difficult to secure? Does spending growth slow more than currently expected? And most importantly … do price, volume, and volatility signals confirm that the weakness is spreading?
We do not need to declare that the AI buildout has ended to recognize that its financing and rate of change deserve close attention. We will let the signals guide our response as that evidence develops.
Following decision points
That brings us back to what we actually do.
As mentioned above, several weeks ago we began reducing our Russell 2000 exposure through IWM and ultimately exited the position. As we discussed last month, small caps can often outperform in Quad 2 … that tendency did not override our signals.
That tendency did not override our signals.
More recently, we have reduced QQQ and technology exposure at specific decision points. With Nasdaq volatility elevated and prices near those levels, paring exposure allows us to manage risk while watching which direction the market takes.
Our SPY positioning remains in place. As of this writing, SPY is approximately 1.2% above our relevant decision point, a distance we remain comfortable with for now.
Different exposures are producing different decisions.
Could markets make another run higher before the projected slowdown? Yes. Could the recent weakness represent an earlier transition? Also, yes.
We do not need to commit the portfolio to either prediction. We can retain exposure where signals support it, reduce exposure where they weaken, and adjust again as new evidence arrives.
Preparing for Quad 4 does not require treating every investment as though Quad 4 has already arrived.
It requires knowing what we own, where our decision points sit, and following the process when those points are reached and possibly breached.
Final thoughts
The minesweepers’ work continued as the operation progressed … a route that had been checked still required attention.
Our investment process requires that same willingness to keep checking.
October’s data support parts of the fourth-quarter acceleration framework we discussed in September. They also reveal meaningful differences beneath the aggregate numbers, while forward projections point toward a more challenging environment in early 2027.
We will remain mindful of those risks. We will also remain willing to participate where our signals support doing so.
That discipline belongs in a financial plan, too. Retirement income, spending needs, taxes, and family circumstances establish the objectives. Changing conditions require us to revisit how those objectives are funded.
When was the last time your plan … and the investments supporting it … were reviewed against the life you are living now and the retirement you are preparing for?
If something has changed, or you would like a clearer understanding of where you stand, schedule your free consultation today.
As always ... Good investing!
Mitchel C. Krause
Managing Principal & CCO
4141 Banks Stone Dr.
Raleigh, NC. 27603
phone: 919-249-9650
toll free: 844-300-7344
Please click here for all disclosures.
This publication is for informational purposes only and is not investment, tax, or legal advice. Investing involves risk, including possible loss of principal. Forecasts are estimates and may change. Risk management does not eliminate investment risk or guarantee against loss.